

Table of Contents
- What a Public Adjuster Does for Commercial Property Damage
- Documenting Commercial Property Damage: A Step-by-Step Approach
- Business Interruption Claim Preparation: What Carriers Expect
- How Public Adjuster Fee Structure Works (and What You Actually Pay)
- When to Hire a Public Adjuster for Commercial Property Claims
- Negotiating With Insurance Carriers: Settlement Strategies That Work
- Pre-Loss Preparation: Reducing Risk Before Damage Happens
- Frequently Asked Questions
Last Updated: September 14, 2026
What a Public Adjuster Does for Commercial Property Damage
A public adjuster for commercial property damage is a licensed professional who represents the policyholder, not the insurance company, through every stage of a property insurance claim. At Public Adjusters Atlanta, our role is to document the scope of loss, interpret commercial policy provisions, and negotiate the settlement you are owed after fire, water, storm, or business interruption damage.
The distinction matters more than most business owners realize. When you file a claim, the insurance carrier assigns its own insurance adjuster to assess your damage. That person is paid by the carrier. Their findings shape the first settlement offer, and that offer is frequently lower than the full scope of loss because damage that is not documented does not get paid.
A public adjuster works exclusively for you. That means damage assessment, claim documentation, proof of loss preparation, and settlement negotiation all happen with your interests as the only priority. Georgia Office of Commissioner of Safety and Fire Prevention licensing information confirms that public adjusters must be licensed in the state where they operate, which is why verifying credentials is the first step before signing anything.
Legal vs. Adjuster Roles: Who Does What
Public adjusters and attorneys play different roles in a commercial claim, and knowing the boundary saves you money. A public adjuster handles the insurance side: inspecting damage, building the scope of loss, filing the claim, and negotiating with the carrier. An attorney steps in when the dispute moves toward litigation, bad-faith claims, or legal action against the insurer.
For most commercial claims, you need an adjuster, not a lawyer. The appraisal process built into most commercial policies resolves valuation disputes without litigation. Attorneys become necessary when a claim denial involves a coverage interpretation fight or when the carrier’s conduct itself becomes the issue.
One caveat: some states restrict what a public adjuster can do once an attorney is involved. If your claim is already in litigation, confirm the working arrangement before hiring both.
Documenting Commercial Property Damage: A Step-by-Step Approach
Documentation wins or loses commercial claims. Carriers pay what they can verify, and a claim built on incomplete records invites underpayment. The process below is the same sequence our team follows on every commercial file.
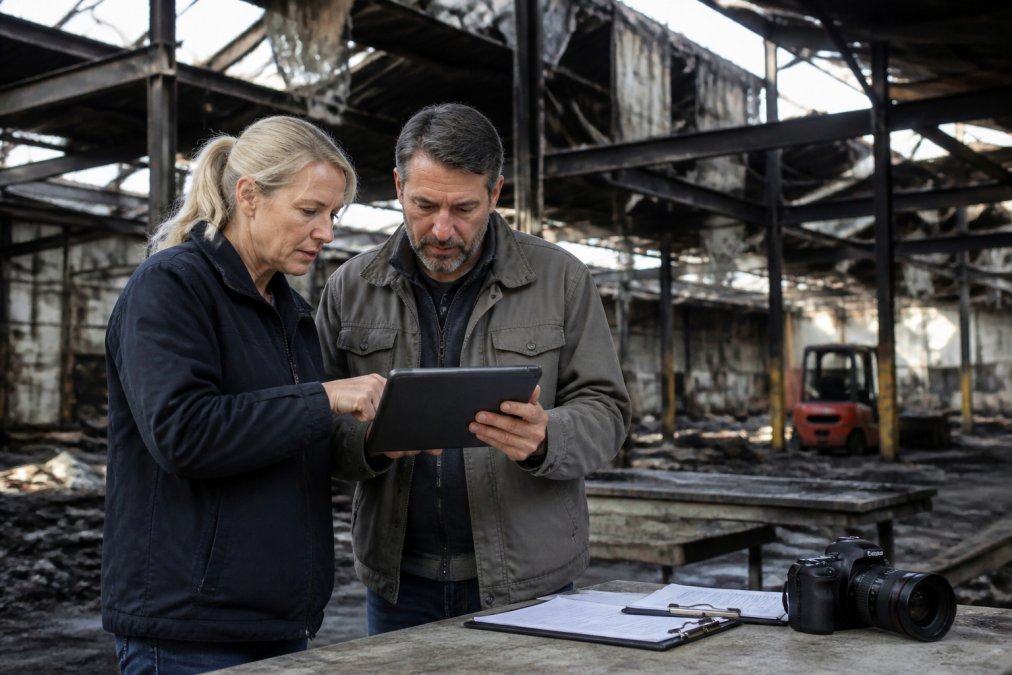
- Secure the property and stop further damage. Loss mitigation comes first. Board windows, tarp roofs, and shut off water. Keep every receipt; mitigation costs are typically recoverable.
- Photograph and video everything before cleanup. Wide shots of each room or zone, then close-ups of structural damage, inventory loss, and equipment.
- Inventory damaged and destroyed items. Itemized lists with purchase dates, model numbers, and replacement values hold up far better than lump-sum estimates.
- Collect financial records. Leases, payroll, tax returns, and profit-and-loss statements establish both property value and income loss.
- Get independent damage assessments. Contractors and engineers can identify structural damage that a visual walkthrough misses.
- Preserve damaged items until the adjuster inspects. Discarding evidence too early is one of the most common and costly mistakes.
Building a Scope of Loss That Holds Up
A scope of loss is the itemized record of everything damaged, what it costs to repair or replace, and how each figure was calculated. Carriers challenge scopes that rely on estimates alone. They accept scopes backed by contractor bids, engineering reports, and dated photographs.
What most guides miss is that the scope of loss is a negotiation document, not a formality. Every line item you can substantiate with a receipt, bid, or report is a line item the carrier has to either pay or formally dispute. Vague claims get trimmed; documented claims get paid.
Business Interruption Claim Preparation: What Carriers Expect
Business interruption coverage replaces lost income while your property is unusable, and carriers scrutinize these claims harder than any other part of a commercial policy. Expect to prove three things: that the damage caused the shutdown, how much income you lost, and how long restoration reasonably takes.
A business interruption claim preparation file typically includes:
- Historical financial statements showing pre-loss income
- Projected income for the interruption period
- Fixed expenses that continued during the shutdown
- A restoration timeline from your contractor
- Documentation of extra expenses, such as temporary relocation
Many businesses find that the gap between what they claim and what gets paid comes down to the restoration timeline. Carriers push for shorter periods; your contractor’s schedule is the evidence that supports a longer one. Line up that documentation early, because once you accept a settlement, reopening the income portion of the claim is difficult.
How Public Adjuster Fee Structure Works (and What You Actually Pay)
Most public adjusters work on a contingency fee: a percentage of the settlement they recover, with nothing owed upfront. That structure aligns incentives, because the adjuster earns more only when you recover more. But the percentage itself is where commercial claims differ from residential ones, and where most business owners get surprised.
Contingency fees mean your out-of-pocket cost at the start of a claim is typically zero. The fee comes out of the final settlement, not your pocket.
How the Fee Is Actually Calculated
The fee is almost always a percentage of the gross settlement, not the net recovery. That distinction matters. If your carrier pays $500,000 and the fee is 10%, the adjuster’s fee is $50,000, calculated before any mortgage payoff, equipment lien, or other deduction. Ask any firm to state plainly whether their percentage applies to the gross or net figure before you sign.
A second mechanic most guides skip: the fee percentage is often tiered or negotiable on larger commercial losses. A $40,000 retail claim and a $4 million manufacturing claim do not carry the same economics for the adjusting firm, and many firms will quote a lower percentage on the larger file. There is no harm in asking for a tiered structure in writing.
State Caps and Why They Differ
Fee percentages are capped by state law in many states, and the cap frequently differs for residential versus commercial claims. Some states set a flat maximum; others set a sliding scale that drops as the claim size rises. Because those limits are set at the state level and change, confirm the current cap and the exact percentage in your written contract before signing. A legitimate public adjuster will put the fee, the scope of representation, and the cancellation terms in writing.
The Contract Terms That Matter More Than the Percentage
The percentage is the headline number, but three contract terms decide whether the arrangement actually protects you:
- Scope of representation. Does the contract cover only the property damage portion, or does it also cover the business interruption claim? A single percentage applied to both is common, but confirm it in writing.
- Cancellation window. Most states require a written right to cancel within a set number of days after signing. Know that window before you sign.
- Fee on minimal recovery. What happens if the adjuster finds nothing beyond the carrier’s original offer? Ask that directly during your initial consultation. Reputable firms explain their policy on minimal-recovery claims in plain terms before you commit. If a firm dodges that question, walk away.
What the Fee Actually Buys
The honest way to evaluate the fee is against the underpayment it prevents, not against the settlement total. A commercial claim that is underpaid by 20% because the scope of loss was incomplete costs far more than a 10% contingency fee. The fee is only expensive when the adjuster fails to move the number, which is exactly why the minimal-recovery question matters so much.
When to Hire a Public Adjuster for Commercial Property Claims
Hire a public adjuster when the claim is large, complex, or already disputed. Three situations justify representation almost immediately:
- The claim involves business interruption. Lost income calculations are where underpayment is most common.
- The carrier denied or underpaid the claim. A denial is not final. Denials are frequently overturned when the policyholder produces better documentation or challenges the coverage interpretation.
- The damage is extensive. Structural damage, inventory loss, and multi-building claims overwhelm most owners handling them alone.
For a small, straightforward claim with a cooperative carrier, self-representation can work. For anything involving loss of income or a disputed scope, the fee usually costs less than the underpayment it prevents.
Signing a carrier’s settlement release ends your ability to reopen the claim. Do not sign anything until you have an independent damage assessment and a full accounting of your business interruption losses.
Negotiating With Insurance Carriers: Settlement Strategies That Work
Settlement negotiation is a documentation contest, not a conversation. The adjuster who arrives with engineering reports, contractor bids, and complete financial records negotiates from strength. The one who arrives with opinions negotiates from hope.
Effective strategies our team relies on:
- Submit a complete proof of loss the first time. Incomplete submissions give carriers grounds to delay and revise downward.
- Dispute specific line items, not the total. Itemized challenges are harder to dismiss than blanket objections.
- Use the appraisal process when valuation stalls. Most commercial policies include an appraisal clause that resolves value disputes without litigation.
- Keep every communication in writing. Verbal assurances from a carrier adjuster are not binding.
If negotiations deadlock over what the policy covers rather than what the damage is worth, that is the point to bring in legal counsel. Coverage disputes and valuation disputes follow different paths.
Pre-Loss Preparation: Reducing Risk Before Damage Happens
The best time to prepare a commercial claim is before you have one. This is the section most guides skip entirely, because pre-loss preparation does not sell adjusting services the way a disaster response does. But it is the single highest-leverage thing a business owner can do, and the mechanism is straightforward: carriers pay what they can verify, and verification is far easier when the records already exist.
Businesses that document their property and finances continuously recover faster and settle higher than those scrambling for records after a fire or flood. The reason is not that carriers are generous to prepared owners, it is that a prepared owner can produce a complete proof of loss on the first submission, and an incomplete submission is the most common trigger for delay and downward revision.
The Pre-Loss File: What to Build and Why Each Piece Matters
A practical pre-loss file includes:
- Updated photo and video inventory of the property, refreshed annually
- Equipment schedules with model numbers, purchase dates, and values
- Three years of financial statements stored off-site and in the cloud
- A current business interruption worksheet estimating daily lost income
- Copies of leases, mortgages, and the full commercial policy
- A contractor contact list for emergency mitigation
Each item maps to a specific claim mechanism. The photo inventory defeats the carrier’s argument that damage pre-existed the loss. The equipment schedules establish replacement cost without a fight over model numbers. The financial statements are the foundation of any business interruption calculation. The business interruption worksheet, the item almost no owner has, converts a vague lost-income claim into a daily figure the carrier has to either accept or formally dispute.
The Underinsurance Trap
Review your policy limits annually against current replacement costs. Underwriting based on outdated property values is one of the quietest causes of underpayment, because the limit itself caps what the carrier can pay regardless of how well you document the loss. A building insured at 2019 construction costs may be underinsured by a wide margin after several years of material and labor inflation, and no amount of documentation can recover past the limit.
This is also where coinsurance clauses bite. Many commercial policies include a coinsurance requirement that penalizes policyholders who insure below a specified percentage of replacement value. If your limit has drifted below that threshold, the carrier can reduce your payout proportionally, even on a fully documented claim. Check the coinsurance percentage in your policy and compare it against a current replacement cost estimate.
A Pre-Loss Walkthrough You Can Do This Quarter
Once a year, walk the property with a camera and a checklist. Photograph every room, every piece of major equipment, and every storage area. Note the date. Store the file off-site. Then pull your policy and confirm three numbers: the property limit, the business interruption limit, and the coinsurance percentage. If any of the three looks stale, that is a conversation to have with your broker before a loss, not after.
Store your pre-loss file somewhere other than the insured property. A cloud backup plus a physical copy at an off-site location means a fire or flood cannot destroy the records you will need to prove your claim.
The unique angle here is simple: most commercial claim content is reactive, written for the owner who already has damage. The owners who recover best are the ones who did this work in a quiet quarter, months before anything happened.
Frequently Asked Questions
How does a public adjuster assist with business interruption claims?
A public adjuster helps you quantify lost income, extra expenses, and ongoing costs during the restoration period. They review your commercial policy provisions, build a business interruption claim preparation file that carriers accept, and negotiate the settlement on your behalf. This includes documenting revenue loss, payroll continuity, and temporary relocation costs so your claim reflects the full financial impact, not just the physical damage.
What is the average fee for a public adjuster?
Public adjuster fee structure varies by state and claim complexity. Most work on a contingency fee, meaning they are paid a percentage of the final settlement, so there is no upfront cost. The exact percentage depends on your policy, the size of the claim, and your state’s regulations. Ask for a written fee agreement before signing anything, and confirm what happens if no additional settlement is recovered.
What are the potential downsides of hiring a public adjuster for commercial claims?
The main trade-off is the contingency fee, which reduces your net settlement. Some policyholders also prefer to handle smaller claims themselves to avoid sharing the payout. However, for complex commercial property damage involving business interruption, structural damage, or inventory loss, a public adjuster often recovers enough additional funds to outweigh the fee. Weigh the fee against the gap between the carrier’s initial offer and the documented loss.
When is the right time to hire a public adjuster after property damage?
Hire one as soon as possible after the damage occurs, ideally before you sign any proof of loss or accept a settlement. Early involvement lets the adjuster document commercial property damage while the site is untouched, preserve evidence, and guide your claim filing from the start. If your claim has already been denied or underpaid, a public adjuster can still review the decision and pursue a revised settlement through negotiation or the appraisal process.