
Most American property owners in the Atlanta metro area are shocked to learn that insurance claim denials affect nearly one out of every five damage cases each year. Facing a denied claim can leave homeowners and small business owners feeling powerless against large insurance companies. Understanding the critical difference between public adjusters and other industry professionals can mean the difference between an underpaid settlement and fair compensation for your property loss.
Table of Contents
- Definition of Public Adjusters and Common Misconceptions
- Types of Adjusters and Key Differences
- Licensed Public Adjusters: Qualifications and Legal Requirements
- Claims Process: Damage Assessment and Negotiation
- Policyholder Rights and Public Adjuster Responsibilities
- Risks, Fees, and Avoiding Costly Mistakes
Key Takeaways
| Point | Details |
|---|---|
| Public Adjusters Role | Public adjusters represent policyholders in insurance claims, helping to maximize settlements through expert negotiation and documentation. |
| License Verification | Always verify a public adjuster’s licensing status and credentials to ensure you are working with a qualified professional. |
| Understanding Fees | Public adjusters typically charge fees up to 15% of the total settlement; evaluate this cost against your potential recovery before hiring one. |
| Policyholder Rights | Policyholders have rights to transparent communication and professional representation from public adjusters during the claims process. |
Definition of Public Adjusters and Common Misconceptions
A public adjuster is an independent insurance professional who represents policyholders during complex insurance claim processes. Unlike insurance company adjusters who work for the insurer, public adjusters exclusively work on behalf of property owners to help maximize their insurance settlements. Public adjusters negotiate and settle first-party claims for loss or damage to personal or real property.
The primary role of a public adjuster involves comprehensive claim management. This includes documenting property damage, interpreting insurance policy language, preparing detailed damage reports, estimating repair costs, and negotiating with insurance companies to secure fair compensation. Public adjusters typically charge a percentage-based fee, usually up to 15 percent of the final settlement amount, which means their compensation is directly tied to the claim’s success.
Despite their valuable services, several misconceptions persist about public adjusters. Many homeowners mistakenly believe that insurance company adjusters will automatically provide a fair settlement or that hiring a public adjuster is unnecessary. In reality, insurance professionals recommend verifying an adjuster’s qualifications and carefully reviewing contract terms to ensure legitimate representation. Public adjusters are licensed professionals who provide an essential service in helping policyholders navigate complex insurance claims.
Pro tip: Always request proof of licensing and references before hiring a public adjuster to ensure you are working with a qualified and reputable professional.
Types of Adjusters and Key Differences
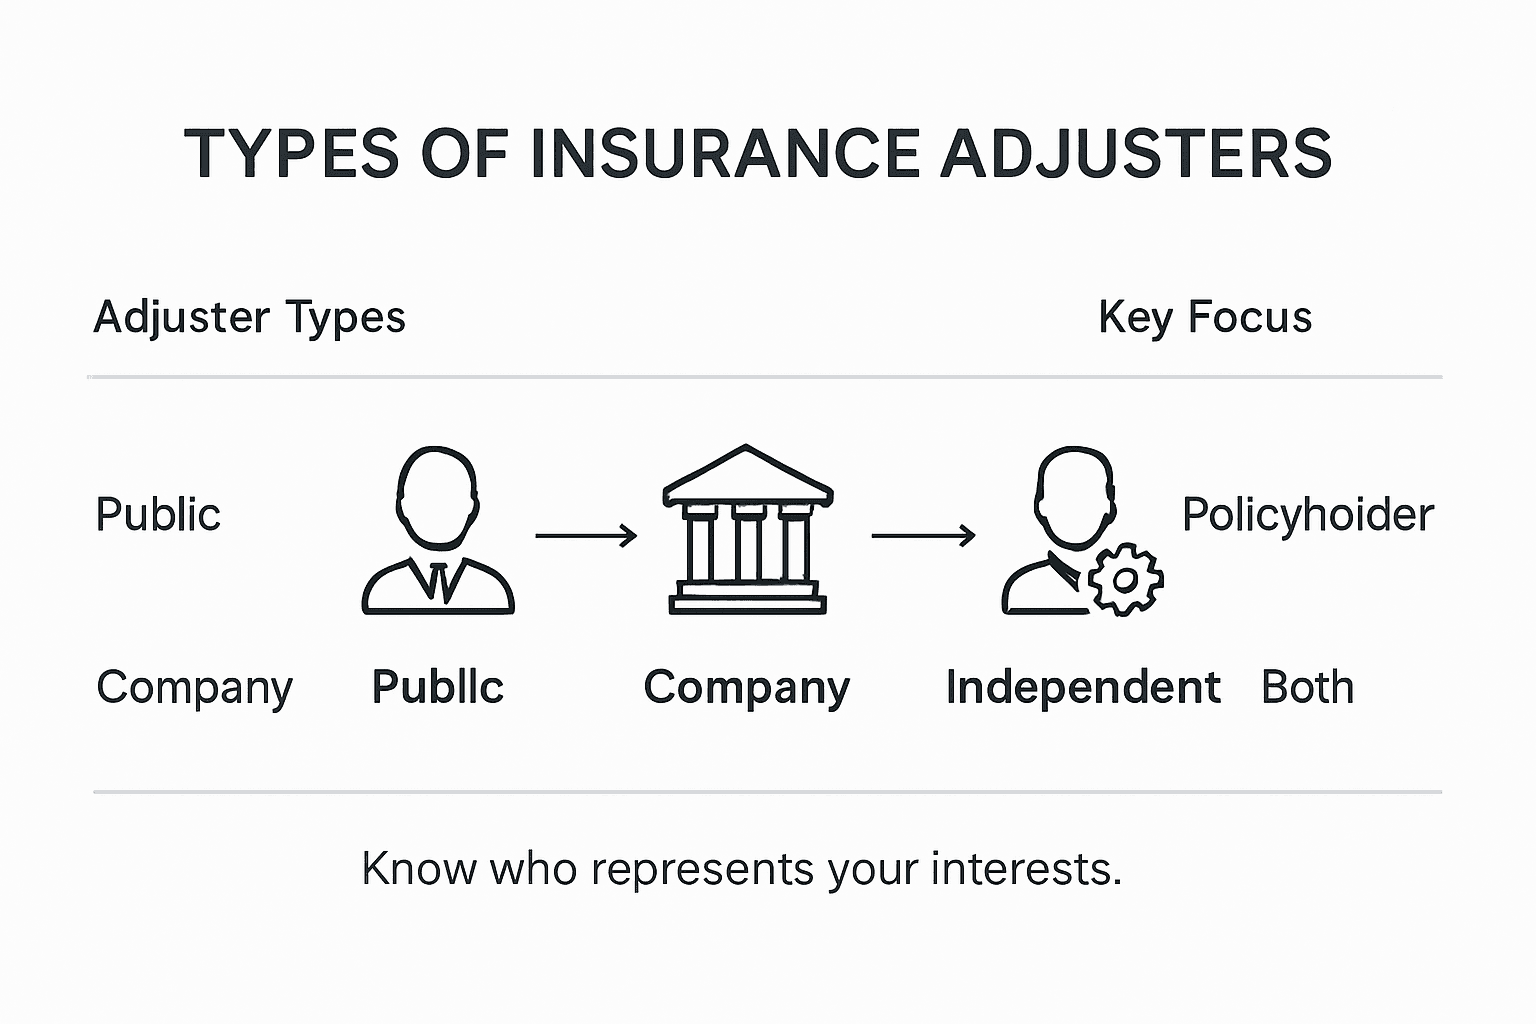
Insurance adjusters play critical roles in property damage claims, with three primary professional categories: public, independent, and company adjusters. Each type serves distinct functions within the insurance claims ecosystem. Insurance adjusters fundamentally evaluate claims and determine payout amounts through different organizational structures and professional responsibilities.
Company (staff) adjusters work directly as salaried employees for specific insurance providers. Their primary objective is protecting the insurer’s financial interests by carefully assessing claims and minimizing potential payouts. Independent adjusters operate differently, working on a contractual basis and often representing multiple insurance companies simultaneously. They provide flexibility for insurers during high-volume claim periods or in specialized geographic regions.
Public adjusters stand apart as the only adjuster type exclusively representing policyholders. These licensed professionals advocate for property owners during complex insurance claim processes, helping them navigate intricate policy language and negotiate fair settlements. Unlike company or independent adjusters who prioritize insurance company interests, public adjusters work directly for homeowners and businesses to maximize potential claim recoveries.
Pro tip: Always verify an adjuster’s licensing status and specific professional affiliation before engaging their services to understand their primary responsibilities and potential conflicts of interest.
Here’s a quick comparison of the three main types of insurance adjusters and their roles:
| Adjuster Type | Who They Represent | Main Objective | Business Impact |
|---|---|---|---|
| Public Adjuster | Policyholders | Maximize claim settlement | Increases payout for property owners |
| Company Adjuster | Insurance companies | Limit insurer liability | Controls costs for insurance firms |
| Independent Adjuster | Multiple insurers | Flexible claim assessment | Aids high-volume coverage periods |
Licensed Public Adjusters: Qualifications and Legal Requirements
Public adjuster licensing represents a critical regulatory framework designed to protect consumers and maintain professional standards in the insurance claims industry. The Public Adjuster Licensing Model Act establishes comprehensive qualifications and legal requirements that ensure these professionals meet rigorous professional standards before representing policyholders in insurance claims.
To become a licensed public adjuster, professionals must navigate a complex set of state-level requirements. These typically include completing mandatory education programs, passing comprehensive licensing examinations, and maintaining ongoing professional credentials. Most states require public adjusters to pass a state-administered exam that tests knowledge of insurance regulations, claim assessment procedures, ethical standards, and legal responsibilities. Additionally, adjusters must typically submit to background checks, provide proof of professional bonding, and demonstrate financial responsibility.
State insurance commissioners oversee the licensing process for public adjusters, ensuring that only qualified professionals can represent policyholders. Continuing education is a critical component of maintaining licensure, requiring adjusters to stay current with changing insurance laws, emerging claim assessment techniques, and evolving regulatory requirements. These professionals must also adhere to strict ethical standards, including maintaining written contracts that clearly define their services, fee structures, and fiduciary responsibilities to clients.
Pro tip: Always request and verify a public adjuster’s current state license and professional credentials before engaging their services to ensure you are working with a fully qualified professional.
Claims Process: Damage Assessment and Negotiation
Property damage claims involve a complex, systematic approach to documenting and valuing losses. The damage assessment process requires methodically evaluating property damage to determine the full extent of loss and support potential insurance settlements. Public adjusters play a critical role in transforming initial damage observations into comprehensive, compelling claim documentation that maximizes potential compensation.
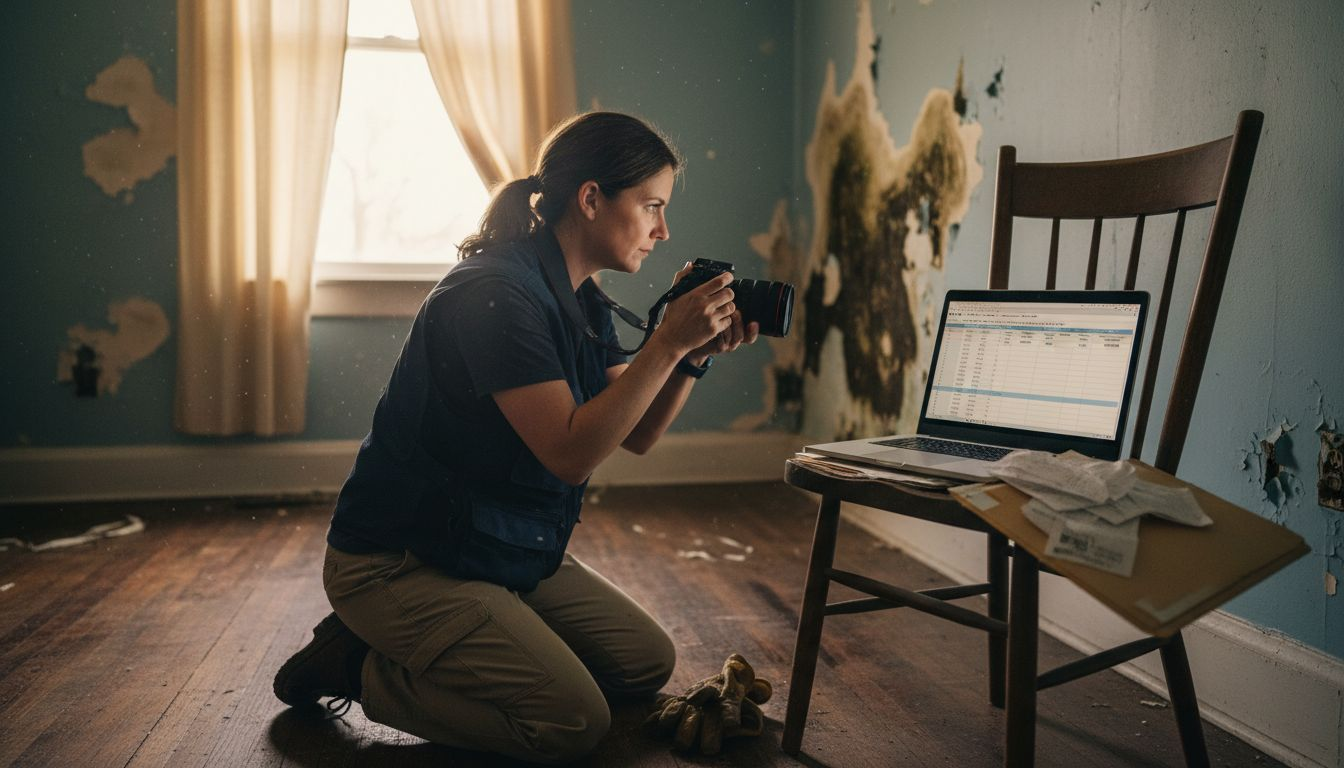
The initial damage assessment involves a meticulous inspection that goes far beyond surface-level observations. Professional adjusters conduct detailed walkthroughs, measuring and documenting every aspect of property damage, including structural impacts, material deterioration, and potential hidden damages. They compile extensive evidence through photographs, measurement records, repair estimates, and expert evaluations that create a comprehensive narrative of the property’s condition before and after the damaging event.
Public adjusters assist policyholders by preparing detailed claim packages that strategically negotiate with insurance companies to secure fair settlements. This negotiation process involves presenting carefully assembled documentation, interpreting complex policy language, and advocating for the policyholder’s maximum entitlements. When initial settlement offers appear insufficient, adjusters may engage in alternative dispute resolution techniques or provide expert testimony to substantiate the claim’s full value.
Pro tip: Maintain a comprehensive photographic and documentary record of all property damage immediately after an incident, as this evidence becomes crucial during the claims assessment and negotiation process.
Policyholder Rights and Public Adjuster Responsibilities
Insurance claim advocacy involves a complex legal and ethical framework that defines the critical relationship between policyholders and public adjusters. Public adjusters have fundamental fiduciary responsibilities to represent policyholders faithfully during first-party claim negotiations, ensuring that the insured’s interests remain the primary focus throughout the claims process.
Policyholders possess specific rights when engaging public adjusters, including the expectation of transparent communication, comprehensive loss documentation, and professional representation. These rights are protected through strict licensing regulations and professional conduct standards that mandate clear contract terms, fee disclosures, and prohibition of conflicts of interest. Public adjusters must provide detailed explanations of their services, fee structures, and potential claim outcomes, empowering policyholders to make informed decisions about their insurance claims.
Policyholders have the legal right to hire licensed professionals who can thoroughly document losses and negotiate settlements on their behalf, ensuring fair compensation for property damages. The responsibilities of public adjusters extend beyond mere claim submission, encompassing strategic negotiation, expert evidence compilation, and persistent advocacy to maximize potential claim recoveries. This professional relationship requires mutual trust, with adjusters committed to operating with the highest ethical standards and policyholders maintaining active engagement in the claims process.
Pro tip: Request a comprehensive written agreement that clearly outlines the public adjuster’s specific services, fee structure, and expected responsibilities before initiating any claim representation.
Review this summary of key policyholder rights and public adjuster responsibilities for effective claims:
| Policyholder Right | Adjuster Responsibility | Benefit to Policyholder |
|---|---|---|
| Transparent communication | Explain services & fees clearly | Enables informed decisions |
| Professional representation | Maintain ethical standards | Ensures fair treatment in claims |
| Comprehensive documentation | Prepare detailed damage reports | Strengthens case for higher payout |
Risks, Fees, and Avoiding Costly Mistakes
Insurance claim representation involves complex financial considerations that can significantly impact a policyholder’s recovery process. Public adjusters typically charge fees ranging up to 15% of the total claim settlement, making it crucial for homeowners to carefully evaluate the potential return on their investment and understand the complete fee structure before engaging professional services.
Navigating the potential risks requires thorough due diligence and strategic decision-making. Policyholders must be vigilant about avoiding common pitfalls, such as falling prey to aggressive solicitation tactics or signing contracts without comprehensive understanding. Potential mistakes include neglecting to verify an adjuster’s professional credentials, rushing into agreements, and failing to fully comprehend the fee terms. Key red flags include unsolicited door-to-door approaches immediately following property damage incidents, which often signal potentially unethical recruitment strategies.
The financial dynamics of hiring a public adjuster demand careful calculation and context-specific evaluation. The claim’s total value, complexity of damage, and potential settlement increase must be weighed against the adjuster’s fees. Smaller claims might not justify professional representation, while larger, more complicated property damage scenarios can benefit substantially from expert negotiation. Transparent communication, verified licensing, and a clear understanding of the adjuster’s specific services are fundamental to mitigating financial risks and ensuring a fair, productive claims process.
Pro tip: Request a detailed, written fee agreement that explicitly outlines percentage rates, service scope, and potential additional charges before signing any contract with a public adjuster.
Maximize Your Insurance Claim With Trusted Public Adjusters in Atlanta
Navigating complex insurance claims for property damage can be overwhelming and costly. The challenges highlighted in the article, such as thorough damage assessment, understanding policy language, and negotiating fair settlements, are precisely where professional help makes all the difference. If you feel uncertain about insurer offers or the nuances of coverage, you are not alone. Many homeowners struggle to secure the full compensation they deserve without expert advocacy.
At Public Adjusters Atlanta, our licensed professionals specialize in providing personalized support designed to maximize your claim settlement. Whether dealing with fire, water, storm, or mold damage, our team ensures detailed documentation, transparent communication, and skilled negotiation on your behalf. We stand ready to transform your complex claim into a clear path toward fair reimbursement.
Are you ready to protect your rights and get the full settlement you deserve?
Take action today by visiting Public Adjusters Atlanta to schedule your free damage evaluation. Empower yourself with expert guidance in claims review, policy evaluation, and settlement maximization. Don’t let uncertainty and delays cost you financial recovery. Contact us now for trusted advocacy that puts your interests first.
Frequently Asked Questions
What is the role of a public adjuster in the insurance claims process?
Public adjusters represent policyholders in negotiating and settling insurance claims, ensuring that they receive fair compensation for property damage or loss.
How do public adjusters charge for their services?
Public adjusters typically charge a fee based on a percentage of the total settlement, usually up to 15%, which aligns their compensation with the success of the claim.
What should I look for when hiring a public adjuster?
When hiring a public adjuster, verify their licensing, check references, and carefully review the contract terms to ensure you are working with a qualified professional.
How can a public adjuster maximize my insurance claim settlement?
Public adjusters maximize settlements by providing comprehensive damage assessments, preparing detailed claim documentation, and advocating aggressively during negotiations with insurance companies.