

Table of Contents
- Review Your Insurance Policy Coverage and Limits
- Document All Property Damage Thoroughly
- Property Damage Claim Documentation Checklist
- Gather Evidence at the Accident Scene
- Calculate Your Total Damages and Losses
- How Long Does Insurance Claim Resolution Take
- Public Adjuster vs Company Adjuster: What’s the Difference
- Handle Insurance Adjusters Strategically
- How to Write a Demand Letter for Insurance Claim
- Avoid Common Mistakes in Settlement Negotiations
- Understand Tax Implications of Your Settlement
- Recognize Bad Faith Insurance Practices
- Steps to Maximize Your Settlement: Action Plan
- Frequently Asked Questions
Last Updated: September 18, 2026
Review Your Insurance Policy Coverage and Limits
Understanding your insurance policy is the foundation of helping you maximize insurance settlement. Most policyholders don’t review their actual coverage until after a loss occurs, which is when it’s too late to make changes. Your policy document contains critical information about what damages are covered, what exclusions apply, and what your limits are for different types of claims.
Start by locating your declarations page, which lists your coverage types and policy limits. This page shows your bodily injury limits, property damage limits, and any additional coverages you’ve added. Pay special attention to your deductible amount and any coverage exclusions that might apply to your specific situation. Many policies have special limits on certain items like jewelry, electronics, or business property that are lower than your overall limit.
Review whether you have additional coverage options that might apply to your claim. Business interruption coverage, for example, can compensate you for lost income while your property is being repaired. Water damage coverage varies significantly between policies, and some carriers exclude certain types of water damage entirely. Understanding these nuances before filing your claim helps you present a more complete picture to the insurance adjuster.
Check your policy for endorsements or riders you may have added over the years. These often provide additional coverage that many policyholders forget they have, which can significantly increase your settlement potential.
Document All Property Damage Thoroughly
Documentation is the currency of insurance claims. The more detailed and organized your evidence, the stronger your position during settlement negotiations. Insurance adjusters rely heavily on documentation to justify their damage assessments, and thorough records make it harder for them to undervalue your claim.
Begin documenting immediately after the loss, if it’s safe to do so. Take photographs and videos of all damaged property from multiple angles and distances. Capture close-ups of specific damage, wide shots showing the overall extent of the loss, and detail shots that show how items were damaged. Include photos of undamaged items in the same room for context, as this helps establish what the space looked like before the loss.
Create a detailed inventory of all damaged items, including descriptions, approximate age, and replacement cost. For high-value items, gather original receipts, credit card statements, or bank records showing the purchase. For items where you don’t have receipts, research current replacement costs for comparable items and document your research. This inventory becomes critical evidence when negotiating with the insurance company.
Preserve all damaged property until your claim is settled. Insurance adjusters often want to inspect items in person, and removing or disposing of damaged goods can undermine your claim. If you must remove items for safety reasons, photograph them first and document why removal was necessary.
Property Damage Claim Documentation Checklist
A systematic approach to documentation ensures you don’t overlook important evidence. This checklist helps you organize the information that insurance adjusters and settlement negotiations require.
| Documentation Type | Purpose | Timeline |
|---|---|---|
| Photographs and video | Visual evidence of all damage | Within 24-48 hours |
| Inventory list | Itemized record of damaged property | Within 1 week |
| Original receipts | Proof of purchase price and date | Gather immediately |
| Repair estimates | Professional assessment of damage costs | Within 2 weeks |
| Medical records | Documentation of injuries and treatment | Ongoing during treatment |
| Pay stubs and tax returns | Evidence of lost wages | Submit with claim |
| Insurance policy documents | Proof of coverage and limits | Keep accessible |
| Adjuster communications | Record of all interactions | Document throughout process |
Keep all documentation organized in a single location, whether digital or physical. Many property owners benefit from creating separate folders for each category of damage. Maintain copies of everything you submit to the insurance company, and request written confirmation when you provide documents to your adjuster.
Gather Evidence at the Accident Scene
The accident scene contains crucial evidence that establishes how the loss occurred and its extent. The first hours and days after a loss are critical for gathering this evidence, as conditions change rapidly and details fade from memory.
Photograph the accident scene from every angle before cleaning up or making repairs. For fire damage, capture the burn patterns, charring extent, and areas of heaviest damage. For water damage, document water lines on walls, soaked materials, and areas affected by moisture. For storm damage, photograph fallen trees, roof damage, broken windows, and debris patterns. Include establishing shots that show the location and context, not just close-ups of damage.
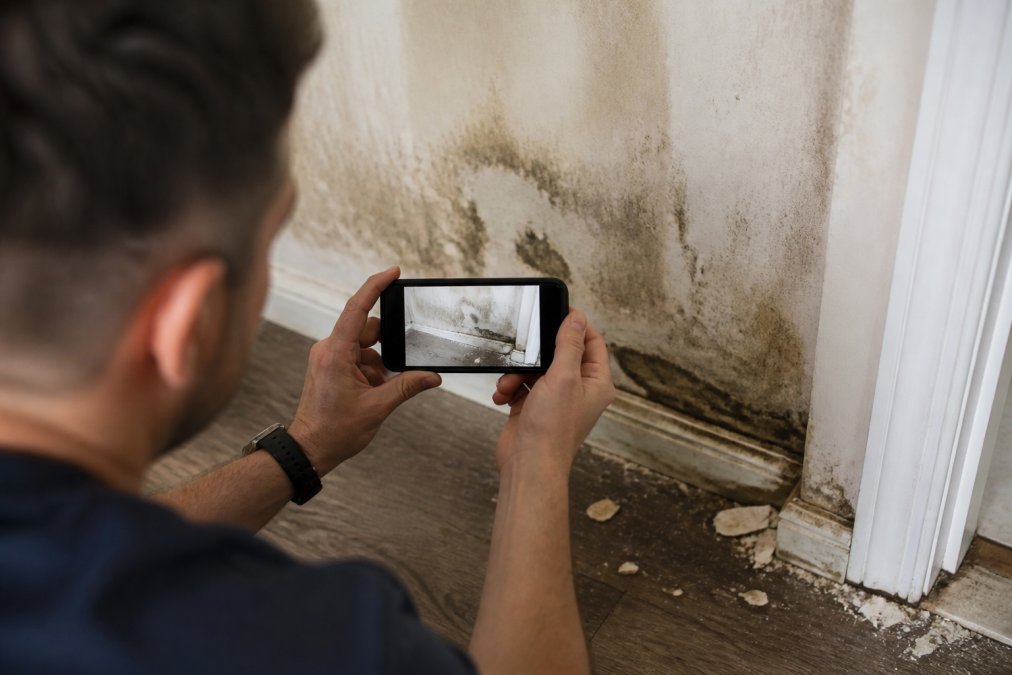
Collect statements from witnesses who saw the incident or its immediate aftermath. Document their names, contact information, and what they observed. These witness statements provide independent verification of how the loss occurred and can support your claim if the insurance company questions the cause of damage.
Preserve physical evidence whenever possible. If a tree fell on your property, keep the tree or large pieces of it until your adjuster has inspected. If a pipe burst, preserve the section of pipe that failed. If an appliance caused a fire, don’t discard it before the adjuster examines it. This physical evidence often reveals important details about the cause of loss that photographs alone cannot capture.
Avoid admitting fault or speculating about the cause of the loss when speaking with witnesses or insurance representatives. Stick to factual descriptions of what you observed. Statements that suggest negligence on your part can be used against you during settlement negotiations.
Calculate Your Total Damages and Losses
Accurate damage calculation is essential for maximizing your settlement. Many property owners significantly underestimate their losses because they overlook certain categories of damage or use outdated replacement costs. A comprehensive damage calculation includes both economic and non-economic losses.
Begin by obtaining professional repair estimates from licensed contractors in your area. Get at least two estimates for major damage, as this provides a range and helps validate the reasonableness of repair costs. Contractors familiar with insurance claims often provide detailed estimates that break down labor, materials, and overhead in ways that support your claim.
For personal property losses, research current replacement costs for items similar to what you lost. Don’t use the original purchase price if those items are no longer available in the same form. Insurance settlements are based on replacement cost or actual cash value depending on your coverage, so current market prices matter more than what you originally paid.
Economic Damages
Economic damages include all quantifiable financial losses resulting from the property damage. These are the most straightforward damages to calculate because they have clear monetary values.
Repair and replacement costs form the largest component of economic damages. This includes the cost to repair or replace damaged structure, systems, and personal property. Labor costs, materials, and contractor overhead should all be included in your repair estimates. For items that cannot be economically repaired, calculate the replacement cost for comparable new items.
Lost wages represent another significant economic damage if the loss forced you to miss work. Document the dates you were unable to work, your hourly rate or salary, and the total income lost. If you’re self-employed, lost business income can be calculated using your business tax returns and accounting records.
Additional living expenses occur when the loss makes your home temporarily uninhabitable. These include hotel costs, restaurant meals, laundry services, and other expenses you incur while living elsewhere during repairs. Keep all receipts for these expenses and categorize them clearly.
Non-Economic Damages
Non-economic damages compensate you for losses that don’t have a direct monetary value but represent real harm from the incident. These damages are more subjective and require careful documentation to support your claim.
Pain and suffering damages account for physical pain, emotional distress, and reduced quality of life resulting from injuries.
Many property owners fail to claim all available non-economic damages because they underestimate the impact of the loss. Document not just the physical damage but also how the loss affected your daily life, work, and well-being.
How Long Does Insurance Claim Resolution Take
Timeline expectations significantly affect how property owners approach settlement negotiations. Understanding the typical process and the factors that drive delays helps you plan your recovery and avoid accepting inadequate settlements out of frustration. However, timelines vary dramatically based on claim complexity, documentation quality, and insurer responsiveness.
Initial Claim Filing and Assignment (3-5 Business Days)
Adjuster Inspection and Initial Assessment (7-21 Days After Filing)
Negotiation and Settlement Phase (2 Weeks to 6+ Months)
Claim agreement level: If you and the adjuster agree on the damage assessment and coverage applies clearly, settlement can occur within 2-4 weeks of the initial offer. If you dispute the damage assessment or coverage, the timeline extends significantly.
Documentation completeness: If you provide detailed repair estimates, receipts, and supporting evidence, the negotiation phase typically takes 3-6 weeks. If you lack documentation, the insurer may request additional information, extending the timeline by weeks or months.
Dispute resolution method: If you and the insurer cannot agree on the settlement amount, you may invoke your policy’s appraisal clause (a neutral process to resolve valuation disputes) or hire a public adjuster. Appraisal typically takes 4-8 weeks. Hiring a public adjuster can extend the timeline by 2-4 weeks but often results in significantly higher settlements.
Insurer responsiveness: Some insurers respond to settlement requests within days; others take weeks. Documenting all communications in writing and following up on unanswered requests accelerates this phase.
Total Timeline Expectations
To accelerate your claim timeline: (1) Respond immediately to all adjuster requests; (2) Provide complete documentation with your initial claim; (3) Schedule your inspection appointment as soon as possible; (4) Obtain your own repair estimates before the adjuster inspection; (5) Follow up in writing on all verbal communications. These actions can compress your timeline by 2-4 weeks.
Public Adjuster vs Company Adjuster: What’s the Difference
Understanding the distinction between these two types of adjusters helps you recognize potential conflicts of interest and make informed decisions about representation. Both roles involve assessing property damage, but their allegiances and incentives differ fundamentally.
Complex claims involving multiple types of damage, business interruption losses, or disputes about coverage are ideal situations for public adjuster representation. If your claim exceeds your deductible by a meaningful amount, the cost of professional representation is typically offset by the additional settlement value they negotiate.
Handle Insurance Adjusters Strategically
Your interactions with insurance adjusters set the tone for your entire claims process. Adjusters are trained negotiators, and how you communicate with them significantly affects their assessment and settlement offer.
How to Write a Demand Letter for Insurance Claim
A demand letter is a formal request for settlement that presents your complete claim to the insurance company. This document serves as the official basis for settlement negotiations and creates a formal record of your claim amount and supporting evidence.
Your demand letter should be factual and professional, not emotional or accusatory. Focus on presenting your damages and supporting evidence rather than criticizing the insurance company or adjuster. A professional tone is more likely to result in a serious counteroffer than an angry letter that puts adjusters on the defensive.
Avoid Common Mistakes in Settlement Negotiations
Property owners often make preventable mistakes during settlement negotiations that cost them thousands of dollars in lost claim value. Recognizing these mistakes helps you negotiate more effectively.
Understand Tax Implications of Your Settlement
The tax treatment of insurance settlements varies significantly depending on the type of loss, the type of damages included in your settlement, and how the settlement is structured. Understanding these implications before accepting a final settlement amount helps you avoid unexpected tax liabilities and allows you to calculate your true net recovery. This is one of the most overlooked aspects of settlement negotiation, yet it can substantially affect your actual financial outcome.
Property Damage to Your Primary Residence (Generally Not Taxable)
Settlements for Lost Business Income (Generally Taxable)
Settlements for Personal Injury (Nuanced Tax Treatment)
Compensation for physical injuries: If you receive a settlement for medical expenses, pain and suffering, or lost wages resulting from physical injuries, this amount is generally not taxable. This applies whether the injuries resulted from a property loss incident (such as being injured in a fire) or from a separate personal injury claim.
Compensation for emotional distress: Compensation for emotional distress, anxiety, or psychological trauma is generally taxable unless it is accompanied by a physical injury or physical manifestation of the emotional distress. If you claim damages for emotional distress resulting from a property loss, and you did not suffer a physical injury, the emotional distress damages may be taxable.
Compensation for lost wages: Compensation for wages you lost due to injury is generally not taxable, as it represents a replacement of wages you would have earned. However, you cannot claim a deduction for the same lost wages on your tax return, you must choose either the settlement or the deduction, not both.
How to Structure Your Settlement to Minimize Tax Liability
Separate business interruption from property damage: If your claim includes both property damage and business interruption losses, request that the settlement clearly separates these amounts. Property damage to your business building may receive more favorable tax treatment than business interruption compensation.
Allocate personal injury damages separately: If your claim includes both property damage and personal injury damages, ensure the settlement clearly allocates amounts to each category. Personal injury damages receive more favorable tax treatment than property damage settlements.
Document the basis of your claim: When you submit your demand letter or settlement proposal, clearly document what each category of damages represents. This documentation supports your tax position if the IRS later questions the taxability of your settlement.
Consult a Tax Professional Before Accepting Settlement
Do not finalize your settlement without understanding its tax implications. A tax professional can often identify strategies to reduce your tax liability or structure your settlement more favorably from a tax perspective. The cost of professional tax advice is typically far less than the tax savings it generates.
Recognize Bad Faith Insurance Practices
Insurance companies have a legal duty to handle claims fairly and in good faith. When insurers engage in bad faith practices, they violate this duty and may expose themselves to liability beyond the claim amount. Recognizing bad faith helps you determine whether you need additional legal remedies.
Steps to Maximize Your Settlement: Action Plan
To maximize insurance settlement, you need a systematic approach that combines thorough documentation, strategic communication, and professional representation when necessary. Start immediately after the loss by documenting all damage with photographs and video, creating a detailed inventory of damaged property, and preserving evidence for adjuster inspection. Within the first week, gather repair estimates from multiple contractors and research replacement costs for damaged items.
Frequently Asked Questions
What documentation is required to maximize a property damage claim?
Comprehensive documentation is critical. Gather photographs and videos of all damage, repair estimates from contractors, receipts for temporary repairs, medical records if applicable, proof of loss, your original insurance policy, the accident report, and a detailed inventory of damaged property with values. Keep organized records of all communication with your insurance adjuster and save copies of every document you submit. This evidence directly supports your claim valuation and strengthens your negotiating position when seeking to maximize your insurance settlement.
How does a public adjuster help increase settlement amounts?
A public adjuster works exclusively for you, not the insurance company. They conduct independent damage assessments, identify coverage you may have missed, prepare detailed documentation, and negotiate directly with the insurer on your behalf. Unlike a company adjuster who represents the insurance company’s interests, a public adjuster advocates to maximize your settlement. They understand policy language, coverage exclusions, and negotiation strategy. Their expertise can help uncover additional damages and ensure you receive fair compensation rather than a low-ball offer.
How long does the insurance claim negotiation process typically take?
Timeline varies by claim complexity. Simple claims may resolve in 30-60 days, while complex property damage claims involving multiple areas of damage or business interruption can take 3-6 months or longer. Initial assessment typically takes 2-4 weeks, documentation and negotiation phases take 4-8 weeks, and settlement discussions may extend several additional weeks. Disputes or denials can significantly extend the timeline. Working with representation can sometimes accelerate the process by ensuring complete documentation upfront and professional negotiation, reducing back-and-forth delays.
What are the signs of a low-ball insurance settlement offer?
Red flags include offers significantly below your repair estimates, settlement amounts that don’t account for all documented damages, quick offers made before thorough inspection, exclusion of non-economic damages, or offers that ignore future medical expenses or business interruption losses. Compare the offer against your documented property damage, medical bills, lost wages, and pain and suffering. If the settlement doesn’t align with your claim valuation and policy limits, request itemized justification. Low-ball offers often rely on you accepting without professional review, this is where expert representation helps ensure you recognize and counter inadequate offers.
What should you never say to an insurance adjuster?
Avoid admitting fault, exaggerating damages, making statements about your financial situation, discussing your insurance history negatively, or agreeing to quick settlements before full assessment. Don’t volunteer information beyond what’s requested, and never accept initial offers without review. Avoid saying you’re desperate for funds or imply you’ll accept any amount. Don’t discuss settlement negotiations with other parties before finalizing. Keep conversations professional and factual. Document everything in writing. These missteps can undermine your negotiation position and result in lower settlements. Professional representation protects you by managing all adjuster communications strategically.
Can a public adjuster overturn an insurance claim denial?
A public adjuster can challenge a denial by presenting new evidence, identifying coverage the insurer overlooked, or demonstrating that the denial was improper. They review the denial reason, gather additional documentation, and resubmit a stronger claim. While they cannot force the insurer to reverse a decision, their expertise often reveals grounds for appeal that policyholders miss alone. If the insurer continues refusing coverage, a public adjuster can help you understand whether bad faith practices occurred or whether pursuing legal action is warranted. Success depends on the denial reason and available evidence.
How do I know if a settlement offer is fair?
Compare the offer against your documented damages, repair estimates, medical bills, and lost wages. Review your policy limits and coverage exclusions to ensure nothing was overlooked. Calculate total economic damages (medical expenses, lost income, repair costs) and non-economic damages (pain and suffering, business interruption). If the offer falls significantly short of these totals, it’s likely low-ball. Request an itemized breakdown from the insurer showing how they calculated the amount. Professional assessment of fair value protects you from accepting inadequate compensation that leaves you undercompensated for actual losses.