

Table of Contents
- What Defines a Complex Commercial Property Claim
- The Role of Claims Specialists and Adjusters
- Preparing a Business Interruption Claim After Property Damage
- Commercial Property Insurance Coinsurance Requirements
- Documenting Property Damage Effectively
- The Commercial Property Claims Process Steps
- Hiring a Public Adjuster for Commercial Claims
- Common Mistakes in Claim Handling
- Communicating with Insurance Carriers
- Technology-Driven Claims Management
- Post-Claim Financial Recovery Strategies
- Understanding the Cash Flow Timeline and Funding Gap
- Interim Financing Options and Cost-Benefit Analysis
- Structuring Claim Settlement for Tax and Cash Flow Efficiency
- Maintaining Operations During the Claims Process
- Establishing Clear Accounting for Claim-Related Expenses
- Planning for Post-Settlement Repayment
- Dispute Resolution Beyond Litigation
- Navigating Multiple Claims and Catastrophic Events
- Frequently Asked Questions
Last Updated: September 25, 2026
What Defines a Complex Commercial Property Claim
Complex commercial property claims involve significant property damage combined with business interruption, multiple coverage types, or disputed valuations that require specialized expertise to navigate. Unlike straightforward residential claims, these situations demand careful documentation, detailed loss calculations, and sophisticated negotiation with insurance carriers who may dispute coverage or undervalue damages.
Complexity emerges from the intersection of technical property assessment, business financial analysis, and insurance contract interpretation. A $500,000 fire loss might be straightforward if damage assessment is clear and business interruption is minimal. A $200,000 water damage claim becomes complex when it triggers coverage disputes, requires proof of causation, involves multiple policy layers, or demands months of reconstruction with significant lost revenue.
Public Adjusters Atlanta works exclusively for policyholders on these intricate claims, which often involve business interruption losses that dwarf the direct property damage. When a commercial kitchen closes for six months due to fire, the lost revenue typically exceeds the cost of replacing equipment. Establishing that loss, documenting it properly, and defending it against insurer skepticism requires specialized expertise.
Common indicators that a claim has crossed into complex territory include coverage disputes, valuation disagreements significantly lower than your documentation, business interruption components, multiple policy layers, or catastrophic damage requiring extensive reconstruction planning.
The Role of Claims Specialists and Adjusters
Insurance adjusters employed by the carrier work for the insurance company, not for you. Their role is to manage the claim within the insurer’s financial interests, evaluating damages, determining coverage applicability, and calculating settlement offers. Their incentive is to settle claims efficiently and affordably from the insurer’s perspective.
A public adjuster works exclusively for the policyholder. Public adjusters are licensed professionals who conduct independent damage assessments, document losses comprehensively, and negotiate directly with the insurance carrier. For complex claims, this distinction matters enormously. The carrier’s adjuster may miss categories of damage, apply policy exclusions too broadly, or undervalue business interruption losses because they lack detailed financial records from your business.
Modern specialists often coordinate with contractors, accountants, and engineers to build a complete loss picture, managing timelines and flagging coverage issues early. For catastrophic events affecting multiple properties, a claims specialist becomes essential for managing the volume of information and coordination required.
Public Adjusters Atlanta focuses on maximizing settlement by ensuring every legitimate loss is identified, documented, and defended. The difference in outcomes between claims handled independently and those with professional representation typically reflects gaps in documentation, underestimated business interruption, or coverage interpretations that favor the insurer’s position.
Preparing a Business Interruption Claim After Property Damage
Business interruption coverage reimburses lost income when property damage forces a business to suspend operations. Preparing this claim requires meticulous financial documentation and a clear timeline connecting the property damage to the revenue loss.
Documenting Lost Income and Operating Expenses
Gather financial records for the 12 months preceding the loss: tax returns, profit and loss statements, bank deposits, and accounts receivable records. For businesses with seasonal variations, this historical context is critical, the insurer will challenge any loss estimate that doesn’t account for typical seasonal patterns.
During the interruption period, document actual revenue lost by tracking what you would have earned versus what you actually earned. If you relocated temporarily and operated at reduced capacity, calculate the difference between normal revenue and actual revenue. Keep detailed records of every customer transaction, contract, or sale that was delayed or cancelled due to the damage.
Operating expenses that continue despite the shutdown are equally important: rent, loan payments, insurance premiums, salaries, and utilities often persist even when the business is closed. Create a spreadsheet documenting daily or weekly lost revenue compared to the same period in the prior year, all continuing operating expenses, payroll, and fixed costs like debt service and lease obligations.
Establishing the Duration of Loss
The duration of business interruption is the period from when damage occurred until the business could resume normal operations. This is not the same as the restoration timeline. If your building was damaged on January 15 but you could have relocated and resumed operations on February 1, the interruption period ends February 1, even if full restoration takes until June.
Obtain written confirmation from contractors about when repairs would be complete and operations could resume. Document any delays caused by supply chain issues, contractor availability, or permitting. For complex claims involving multiple locations or phased reopening, establish separate loss periods for each operational phase.
Commercial Property Insurance Coinsurance Requirements
Coinsurance is a penalty provision in many commercial policies that reduces your recovery if you underinsure the property. The clause requires you to carry insurance equal to a percentage (typically 80% or 90%) of the property’s replacement value. If you carry less, you become a “coinsurer” and share the loss.
The coinsurance formula works like this: if your policy requires 80% coverage and you insured the property at only 70% of its replacement value, you recover only 70/80 (87.5%) of the loss. A $100,000 loss becomes a $87,500 recovery. This penalty applies even if the loss is small relative to the underinsured amount.
Many businesses discover coinsurance penalties only after filing a claim. Preventing this requires accurate property valuation before a loss occurs. Obtain a professional appraisal of replacement cost, not market value. For commercial properties with equipment, inventory, and improvements, replacement cost valuation is complex. Public Adjusters Atlanta ensures that coinsurance calculations are based on accurate valuations, protecting you from penalties that reduce recovery on legitimate claims.
Review your policy’s coinsurance requirement annually, especially if you’ve made significant improvements or acquired new equipment.
Documenting Property Damage Effectively
Effective documentation is the foundation of claim recovery. The insurer will base their settlement on what you can prove was damaged and the cost to repair or replace it.
Creating a Comprehensive Inventory
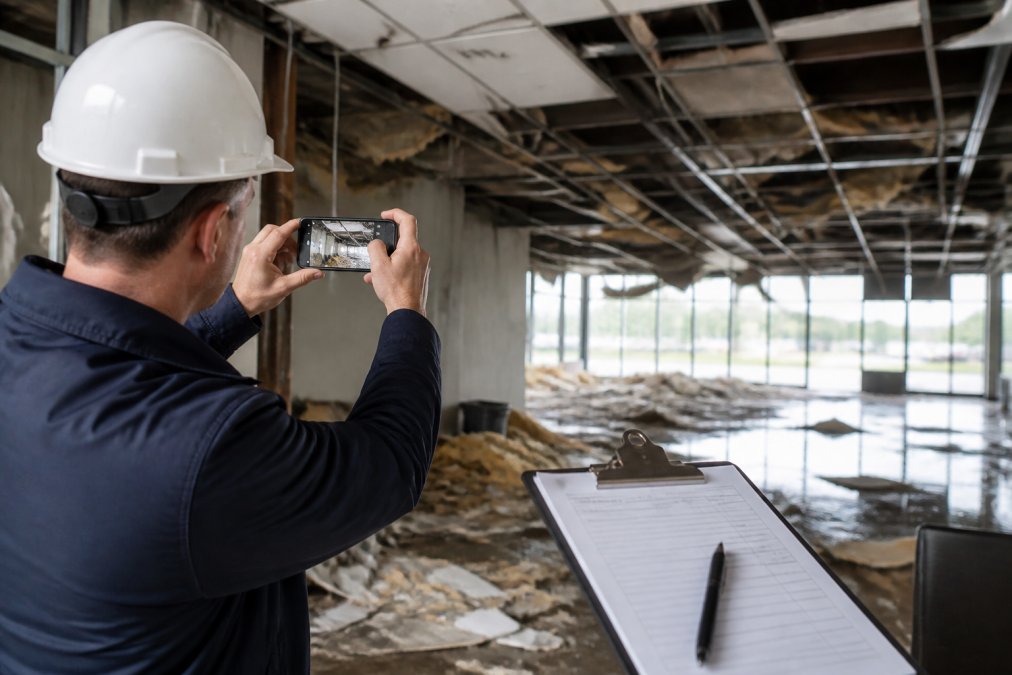
Begin documenting immediately after the loss, before cleanup or repairs begin. Take photographs and video of all damaged areas from multiple angles, including wide shots showing overall damage and close-ups showing specific details. Photograph undamaged areas adjacent to damaged zones to establish context.
For each damaged item, record description, original purchase date if known, condition before the loss, extent of damage, and estimated replacement or repair cost. Create a spreadsheet listing all damaged items by category: building structure, HVAC systems, equipment, inventory, furniture, and fixtures. Include photographs of each category. For high-value items, obtain multiple repair or replacement quotes.
For inventory losses, you’ll need sales records, purchase invoices, and inventory counts to establish what was lost. Maintain current inventory records and consider periodic professional inventory appraisals for high-value stock.
Obtaining Vendor Estimates and Repair Quotes
Contractor estimates are critical evidence of repair costs. Obtain at least two estimates for major repairs or replacements. Ensure estimates are detailed, a vague “$50,000 to repair the roof” is less useful than a line-item estimate specifying materials, labor, and timeline.
For equipment replacement, obtain quotes from the equipment manufacturer or authorized dealers. New equipment quotes establish the true replacement cost. Keep all estimates organized chronologically. For items that cannot be directly replaced, obtain appraisals or expert assessments of replacement cost.
The Commercial Property Claims Process Steps
Understanding the claims process timeline helps you manage expectations and ensure deadlines are met. Missing deadlines can result in claim denial.
Step 1: File the Initial Claim Notification
Notify your insurer of the loss as soon as practicable. Most policies require notice within a specific timeframe (often 30 to 60 days). Provide basic information: date of loss, type of damage, estimated loss amount, and contact information. Keep a copy of your notification and any confirmation the insurer provides.
Step 2: Submit Proof of Loss Documentation
Within a specified period (typically 60 to 90 days), you must submit detailed proof of loss including the inventory, photographs, estimates, and financial records supporting your loss calculation. Proof of loss typically includes detailed description of all damaged property, photographs and video documentation, contractor estimates, receipts or invoices showing original cost or value, financial records and lost income calculations, and proof that the loss was caused by a covered peril.
Submitting comprehensive proof of loss early puts pressure on the insurer to respond substantively. Incomplete or late submissions weaken your position and may trigger claim denial.
Step 3: Participate in the Damage Assessment
The insurer’s adjuster will inspect the damage and prepare their assessment. You have the right to be present during this inspection and to provide your own documentation. Attend the inspection with your own documentation: photographs, estimates, and detailed notes about the damage. Point out damage the adjuster may miss or underestimate.
For complex claims, having a public adjuster present during the carrier’s inspection is valuable.
Step 4: Negotiate Settlement Terms
After the adjuster completes their assessment, the insurer will make a settlement offer. This offer is rarely their final position. Review the offer carefully against your documentation. If the offer is significantly lower than your loss calculation, prepare a detailed response explaining the discrepancies.
Hiring a Public Adjuster for Commercial Claims
Public adjusters are licensed professionals who represent policyholders in claim disputes. For complex commercial claims, professional representation often yields substantially higher settlements than handling the claim independently. Public adjusters work on contingency.
Common Mistakes in Claim Handling
Failing to document the loss immediately is among the most costly mistakes. Photograph everything before cleanup begins. Underestimating business interruption losses is another common error, many businesses focus on property restoration and overlook lost revenue. If you don’t document lost income contemporaneously, proving it months later becomes difficult.
Communicating with Insurance Carriers
Maintain professional, documented communication. Email is preferable to phone calls because it creates a record. When you call, follow up with an email summarizing what was discussed.
Technology-Driven Claims Management
Modern claims management increasingly relies on technology to document, track, and manage loss information. For complex commercial claims, the right technology stack can help reduce settlement timelines and eliminate documentation gaps that insurers exploit to reduce payouts.
Drone Imagery and 3D Property Mapping
Drone photography has become standard for large-loss assessments, particularly for roof damage, industrial facilities, or multi-building properties. Drones capture high-resolution imagery and create orthomosaic maps, stitched aerial photos showing the entire property from above with precise measurements. This documentation is difficult for insurers to dispute because it’s objective, timestamped, and creates a visual record before any cleanup occurs.
Digital Inventory and Loss Quantification Tools
For business interruption claims and inventory losses, specialized software platforms allow you to create detailed, timestamped inventories before a loss occurs. When a loss happens, you can pull exact inventory records showing what was on-site, when it was acquired, and what it cost.
Claims Management Platforms and Workflow Automation
Cloud-based claims management platforms centralize all claim documentation in a single repository accessible to all parties. These platforms create a shared timeline of events, track document submissions and deadlines, and flag when action is required.
Artificial Intelligence for Damage Assessment and Valuation
AI-powered damage assessment tools are emerging as a way to standardize damage evaluation and reduce subjective interpretation. These tools analyze photographs of damage, estimate repair costs based on regional pricing databases, and flag damage patterns that might indicate coverage issues.
Integration Strategy: Building Your Technology Stack
The most effective approach combines multiple tools rather than relying on a single platform. A typical workflow might be: drone assessment for initial documentation, digital inventory tools for baseline property records, accounting software integration for business interruption calculations, and a claims management platform to coordinate all parties and track deadlines.
Post-Claim Financial Recovery Strategies
The claims process often extends over months or years, during which your business must continue operating with reduced revenue and uncertain recovery timing. Developing financial strategies to bridge this gap is as critical as maximizing the claim settlement itself.
Understanding the Cash Flow Timeline and Funding Gap
Most commercial property claims can take months to settle. During this period, your business faces a predictable cash flow crisis: operating expenses continue, but revenue may be reduced or eliminated if the property damage interrupted operations. Map out your specific cash flow timeline: When did the loss occur? When will the property be operational again? When do you expect claim settlement?
Interim Financing Options and Cost-Benefit Analysis
Several financing options can bridge the cash flow gap:
Business Line of Credit offers the fastest interim funding if you have an existing relationship with a lender. Lines of credit typically have lower interest rates than other options. The downside: they require approval before the loss occurs.
Structuring Claim Settlement for Tax and Cash Flow Efficiency
When your claim settles, how the settlement is structured affects your tax position and cash flow. Work with your accountant and the insurer to structure the settlement optimally.
Maintaining Operations During the Claims Process
Minimizing revenue loss during the claims process reduces your funding gap and improves your overall financial position.
Establishing Clear Accounting for Claim-Related Expenses
During the claims process, you’ll incur various expenses: public adjuster fees, contractor estimates, temporary relocation costs, accelerated repairs, and interim financing costs. Establish a separate accounting category for these expenses so you can track them clearly.
Planning for Post-Settlement Repayment
When your claim settles and you receive the recovery, you’ll need to repay any interim financing you used. Plan for this repayment from the settlement proceeds.
Dispute Resolution Beyond Litigation
When negotiation reaches an impasse, formal dispute resolution options exist short of full litigation.
Navigating Multiple Claims and Catastrophic Events
Catastrophic events like major storms or industrial accidents often damage multiple properties simultaneously, creating multiple claims that must be coordinated. Develop a master inventory of all affected properties with damage assessments for each. Prioritize claims by complexity and recovery potential. Simple, straightforward claims should be resolved first, freeing resources for complex claims requiring more attention.
| Claim Phase | Key Actions | Timeline |
|---|---|---|
| Initial Notification | Report loss to insurer, gather basic information | Within 30-60 days of loss |
| Documentation | Photograph damage, create inventory, obtain estimates | 30-90 days |
| Proof of Loss | Submit comprehensive claim documentation | 60-90 days from loss |
| Assessment | Participate in adjuster inspection, provide evidence | 30-60 days |
| Negotiation | Review offer, provide counter-documentation, negotiate | 30-180 days |
| Settlement | Finalize terms and receive payment | Varies by complexity |
Georgia Department of Insurance licensing requirements
National Association of Insurance Commissioners guidance on claims handling
American Institute for Property and Liability Underwriters professional standards
Frequently Asked Questions
What is an example of a complex commercial property claim?
A complex commercial property claim typically involves multiple types of damage (fire, water, structural) combined with business interruption losses. For example, a manufacturing facility damaged by a fire may have equipment replacement costs, building repairs, lost production income, and extra expenses for temporary operations. These claims require detailed documentation of inventory, equipment valuations, proof of income loss, and careful calculation of coverage limits and deductibles to ensure full recovery.
How does the 80% coinsurance clause affect my commercial property settlement?
The 80% coinsurance clause requires you to maintain insurance equal to at least 80% of your property’s replacement value. If you’re underinsured, the insurance company applies a penalty formula to your settlement. For instance, if your property is worth $1 million but you only insure it for $700,000, you’re underinsured by 12.5%, which reduces your claim payout proportionally. Understanding commercial property insurance coinsurance requirements is critical when determining coverage limits to avoid unexpected settlement reductions.
What should I avoid saying to an insurance adjuster during a site inspection?
Avoid admitting fault, speculating about damage causes, or discussing settlement expectations. Don’t minimize damage or make casual statements like ‘it could have been worse’ that might be used against your claim. Never agree with the adjuster’s preliminary damage assessment on the spot. Instead, provide factual information, stick to documented evidence, and let your documentation speak for itself. If you’re uncertain about anything, defer to professional guidance rather than making statements that could be misinterpreted.
What is the role of a public adjuster in handling complex commercial claims?
A public adjuster advocates exclusively for the policyholder, not the insurance company. They conduct independent damage assessments, prepare detailed proof of loss documentation, calculate accurate claim values, and negotiate directly with the insurance carrier on your behalf. For complex commercial claims involving business interruption, multiple coverage types, or high-stakes losses, a public adjuster ensures all damages are identified and properly valued. They manage the entire claims lifecycle, allowing you to focus on business recovery while they fight for maximum settlement.
How long does a complex commercial property claim typically take to resolve?
Timeline varies based on claim complexity, damage extent, and whether disputes arise. Simple claims may resolve relatively quickly, while complex commercial claims involving business interruption, multiple properties, or coverage disputes often take an extended period. Factors affecting duration include documentation completeness, insurance carrier responsiveness, appraisal processes, and whether settlement negotiation or dispute resolution is required. Working with experienced representation can help expedite the process by ensuring all documentation is thorough from the start.
Can a public adjuster overturn an insurance claim denial?
Yes, a public adjuster can challenge a claim denial by conducting an independent investigation, gathering additional evidence, and presenting a compelling case for coverage. Many denials result from incomplete documentation or misinterpretation of policy language. A public adjuster reviews your commercial insurance policy thoroughly, identifies coverage that may have been overlooked, and negotiates with the insurance carrier to reverse the denial. If negotiation fails, dispute resolution options such as appraisal or mediation may overturn the decision without requiring litigation.
What documentation is most critical when preparing a business interruption claim?
Essential documentation includes profit and loss statements for the 12 months before the loss, payroll records, rent or lease agreements, utility bills, accounts receivable records, and evidence of business suspension due to the property damage. You’ll also need documentation of extra expenses incurred during the interruption period, such as temporary location costs or expedited repairs. Detailed records establishing the causal link between the property damage and income loss are vital. The more comprehensive your documentation, the stronger your case for full recovery of lost income and necessary operating expenses.
If your business has a large or complicated loss, our property damage adjuster page explains how commercial claims are handled in Atlanta and who we refer you to first.